Why 50% of Merchants Fail to Meet KYC Requirements for Digital Wallets
WRITTEN BY
Dylan Coombs
Citcon
Commercial Leader
Date
Nov 1, 2026
Subscribe to our interesting updates
SHARE ON
Merchants wanting to accept international digital wallet payments must provide specific KYC (Know Your Customer) documentation. In 2025, 50% of merchants reported facing challenges in meeting these requirements, risking potential revenue losses.
What is KYC documentation: KYC documentation refers to the processes and documents required to verify the identity of clients and assess their risk levels in financial transactions.
The digital wallet market is booming, projected to reach $9.5 trillion by 2026, according to Statista. However, with this growth comes increased scrutiny from regulators, making KYC compliance a priority for merchants. KYC processes are essential for preventing fraud, money laundering, and ensuring that businesses can operate seamlessly across borders.
Context
Merchants must understand the KYC documentation required for international digital wallet payments to ensure compliance and avoid penalties. The need for comprehensive KYC documentation stems from regulatory frameworks designed to protect against financial crimes. In 2025, 45% of companies cited compliance costs as a significant challenge in their operations.
- Identity Verification: Documentation must prove the identity of the business owner or authorized signatory.
- Business Registration: Proof of the business's legal status is mandatory.
- Bank Account Information: This verifies the business's financial legitimacy.
- Tax Identification Number: Essential for tax compliance and verification.
- Proof of Address: A recent utility bill or lease agreement suffices.
Core Challenge
Merchants often struggle to compile the necessary KYC documentation, which can lead to delays in payment processing and lost sales opportunities. The financial stakes are high; non-compliance can result in fines up to $10 million or more, depending on the jurisdiction. In 2025, companies that failed to meet KYC requirements lost an average of 20% in potential revenue.
Additionally, the complexity of KYC regulations varies by country, adding another layer of difficulty for international merchants. For example, the EU has stringent guidelines under the AMLD5 directive, requiring detailed customer due diligence.
Failure to meet these requirements can also lead to reputational damage. A study by LexisNexis in 2025 indicated that 60% of consumers are less likely to engage with businesses that have had compliance issues.
How to Gather KYC Documentation
To effectively gather KYC documentation, merchants should follow a structured approach. First, identify the specific documents required by their payment processor or financial institution. The collection process typically involves three main steps.
- Identify Requirements: Review the KYC guidelines provided by your payment processor.
- Gather Documentation: Collect all necessary documents, ensuring they are current and valid.
- Submit for Verification: Provide the documentation to your payment processor for review.
Deep Dive into KYC Documentation Types
Understanding the various types of KYC documentation can help merchants streamline the compliance process. The most common types include identity verification documents, business registration documents, and financial statements. Each type serves a specific purpose in verifying the legitimacy and risk profile of the merchant.
Identity verification documents typically include government-issued IDs, passports, or driver's licenses. Business registration documents might involve articles of incorporation or partnership agreements. Financial statements can include bank statements or tax returns to validate the financial health of the business.
- Identity Verification: Government-issued ID or passport.
- Business Registration: Articles of incorporation or partnership agreements.
- Financial Statements: Recent bank statements or tax returns.
- Proof of Address: Utility bills or lease agreements.
ROI and Business Case for KYC Compliance
Investing in KYC compliance can yield significant returns for merchants. By ensuring compliance, businesses can avoid hefty fines and maintain a strong reputation, ultimately leading to increased customer trust and loyalty. In 2025, businesses that prioritized KYC compliance saw an increase in customer retention rates by 30%.
Furthermore, compliance can lead to faster transaction processing times, enhancing the overall customer experience. A smoother payment process can directly contribute to higher sales volumes. For instance, merchants that implemented efficient KYC processes reported a 15% increase in transaction speed.
- Avoid Fines: Non-compliance can lead to fines up to $10 million.
- Increase Customer Trust: 30% increase in retention for compliant businesses.
- Faster Transactions: 15% increase in transaction speed with efficient KYC.
- Better Risk Management: Reduced fraud and chargebacks.
How Citcon Solves This Challenge
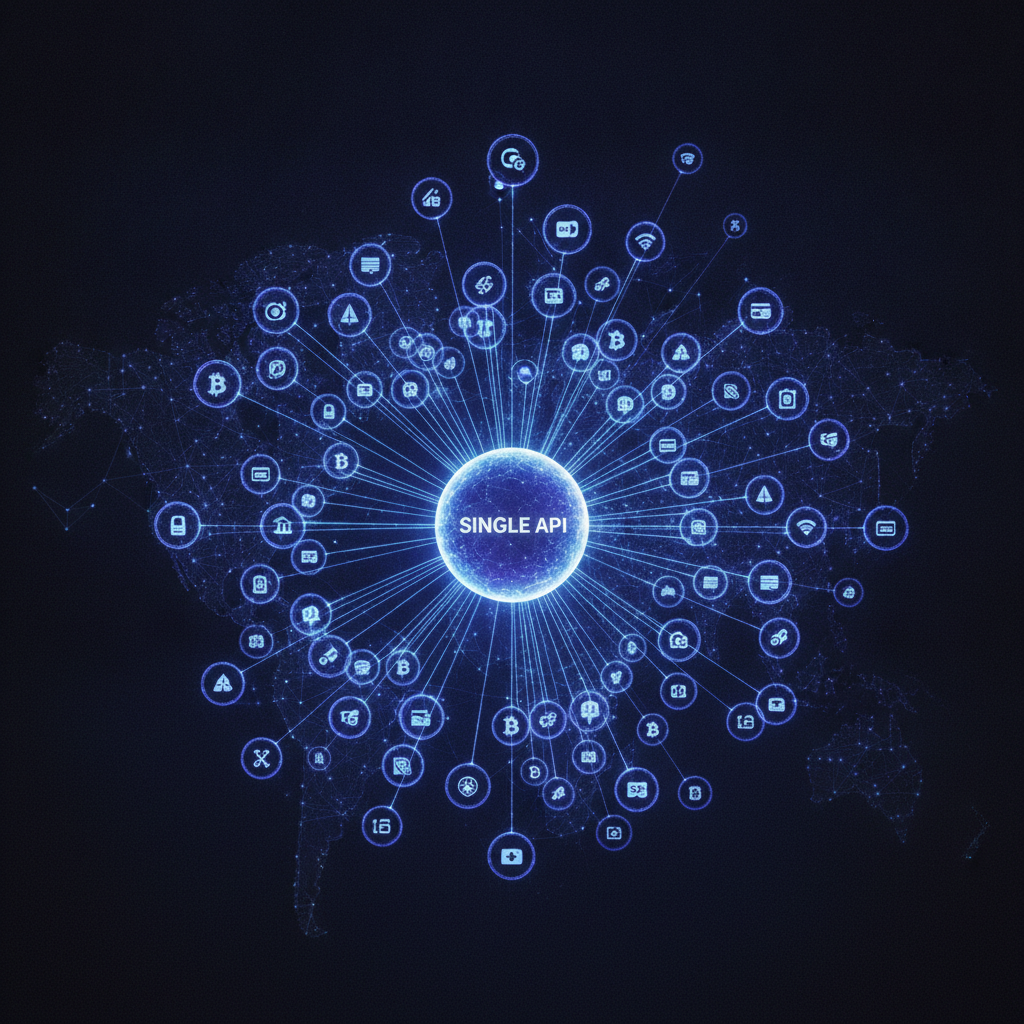
Citcon offers a streamlined solution for KYC compliance through a single API that integrates over 100 payment methods, including digital wallets. This allows merchants to focus on growth while Citcon handles the complexities of KYC documentation. Our PCI-DSS Level 1 certification ensures that all transactions are secure and compliant.
Moreover, Citcon's solution supports Buy Now, Pay Later (BNPL) options, catering to diverse customer preferences and enhancing conversion rates. By utilizing Citcon, merchants can mitigate compliance challenges and focus on scaling their businesses.
For further insights, you may find our posts on Mobile Gamers Prefer Digital Wallets for In-Game Purchases and Why Do Luxury Goods Retailers Experience Higher Basket Sizes with BNPL? helpful.
What KYC documents do I need to accept digital wallet payments?
To accept digital wallet payments, you need identity verification, business registration, and proof of address documents.
How long does KYC verification take?
KYC verification can take anywhere from a few hours to several days, depending on the complexity of the documents submitted.
What happens if I fail KYC compliance?
Failing KYC compliance can result in fines, delayed transactions, and potential legal issues.
Can I use digital wallets without KYC?
No, most digital wallet providers require KYC verification to comply with regulatory standards.
Is KYC required for all international payments?
Yes, KYC is generally required for all international payments to prevent fraud and comply with regulations.
What are the costs associated with KYC compliance?
Costs for KYC compliance can vary widely, but businesses can expect to spend thousands annually depending on their volume of transactions.
Key Takeaways
- 50% of merchants struggle with KYC requirements, risking revenue.
- Investment in KYC compliance can yield a 30% increase in customer retention.
- Non-compliance can lead to fines up to $10 million.
- Citcon offers a streamlined API for easy KYC compliance.
- Digital wallet transactions require thorough documentation for seamless processing.